Credit & debit card processing
Standard card acceptance for established businesses, in person and online, on terms that reflect an ordinary risk profile.
Loading Apex Merchant Solutions
Merchant services and payment technology
Apex brings card, bank, digital-asset and international payment paths together under one merchant relationship - for established businesses, and for the complex ones other providers turn away.
Solutions available based on business type and underwriting. Apex evaluates each merchant's requirements individually.
What Apex handles
Everything listed here is something Apex delivers directly or arranges as part of a merchant relationship. What is available to a specific business depends on underwriting.
Solutions
Most businesses need one of these. Some need four working together. Apex builds the arrangement around how you actually sell, rather than around one processor's product list.
Standard card acceptance for established businesses, in person and online, on terms that reflect an ordinary risk profile.
Checkout that fits the platform a business already runs on, rather than one that forces a rebuild.
Bank-to-bank collection for larger tickets, recurring invoices and anywhere card fees stop making sense.
Digital-asset acceptance with settlement handled as part of the same merchant relationship.
Supported assets and settlement arrangements depend on underwriting and jurisdiction.
The routing layer between a checkout and the processors behind it, configured for how a business actually sells.
Countertop, portable and Android terminals, plus point-of-sale systems for shops, restaurants and service counters.
Exact models and compatibility are confirmed during onboarding.
Alerting, evidence handling and dispute support to keep chargeback ratios under control.
No provider can prevent chargebacks. These tools reduce and manage them.
Account placement for business models generalist providers decline, with the underwriting handled properly first.
Placement, pricing and reserve terms are set by underwriting. Apex does not guarantee approval.
Availability varies by industry and processing profile. Apex reviews each merchant's requirements individually rather than applying a standard package.
Where you sit
The difference between a neighbourhood restaurant and a specialised e-commerce operation is not whether Apex will work with you. It is how much preparation the underwriting takes.
A shop, restaurant or practice taking payment in person. Conventional underwriting, conventional terms.
Card and wallet acceptance at volume, where approval rates and dispute handling begin to matter more than the headline rate.
Repeat billing, where a failed payment costs more than the processing fee on the one that succeeded.
Business models that need a prepared underwriting file, and usually more than one processing path behind them.
Several jurisdictions, several currencies and several settlement routes running at once.
Wherever a business sits on that line, three things do not change.
The same team handles underwriting, integration and what happens afterwards. You are not handed between departments.
Gateway, terminals and reporting work the same way whether the account is conventional or specialised.
When a payment fails or a dispute arrives, you speak to the people who set the account up.
Industries
Apex works across the full range. A restaurant and a research-product supplier are both ordinary customers here - they simply need different underwriting.
Counter, kiosk and multi-site retail, with terminals and reporting that match how the shop actually runs.
Payment infrastructure for peptide and research-product businesses, built around underwriting rather than around a single processor.
Table, counter and delivery service, with tipping, split payments and end-of-day reconciliation handled properly.
Online retail on an established platform or a custom build, with checkout tuned for conversion and disputes kept in check.
Card and bank-based acceptance for CBD and hemp merchants, with the compliance documentation prepared before submission.
Invoiced and retainer billing for firms and consultancies, where ACH usually beats cards on the larger tickets.
Platforms, marketplaces and Web3 businesses that need both fiat acceptance and digital-asset settlement.
Recurring billing where failed payments and involuntary churn matter more than the headline rate.
Dealerships, workshops and parts suppliers, where a single ticket can be large enough to change which rail makes sense.
Supplement merchants with recurring orders, where descriptor clarity and dispute handling decide whether an account survives.
Trade accounts and invoiced orders, where bank-based collection usually costs less than card acceptance.
Selling across borders, where acceptance rates and settlement currency matter as much as the processing rate.
Where a label appears on a card, it describes the shape of the payment arrangement, not the business behind it. A conventional business is not placed on specialised terms because of the other industries Apex serves.
Peptide and research-product merchants are declined constantly - or opened, then offboarded weeks later with funds held. The payments themselves are not the difficult part. The underwriting is, and that is the part Apex prepares.
Apex provides payment infrastructure. We do not evaluate, endorse or verify the products a merchant sells, and nothing here is a medical, therapeutic, health, safety, legal or scientific statement. Processing options depend on underwriting, products, websites, policies and supporting documentation.
Payment rails
Card is the default, not the only option. Choosing the right rail - or running several in parallel - is usually worth more than negotiating the rate on one of them.
The rail most customers expect. Apex handles the terminal or gateway, the underwriting behind it, and the descriptor that decides how many of those payments turn into disputes.
Where the ticket is large or the billing is recurring, ACH usually costs less than a card and is far less likely to be disputed months later.
For customers who still pay by cheque, without anyone driving to a bank.
A settlement path that does not depend on card rails, for businesses whose customers want to pay this way or whose model needs an alternative.
Supported assets and settlement arrangements depend on underwriting and jurisdiction.
Payment paths for platforms that conventional providers decline to underwrite, with the fiat side handled as carefully as the on-chain side.
Availability depends on the platform, the assets involved and underwriting review.
Where routing rules, tokenisation and retry behaviour live. Configured properly, it is usually worth more than any single rate.
Countertop, portable and handheld hardware, matched to how the room actually works rather than to whatever was in the box.
Exact models and compatibility are confirmed during onboarding.
Hardware
A busy counter, a table-service floor and a delivery van each need different hardware. Apex sources to suit, rather than fitting a business to one device.
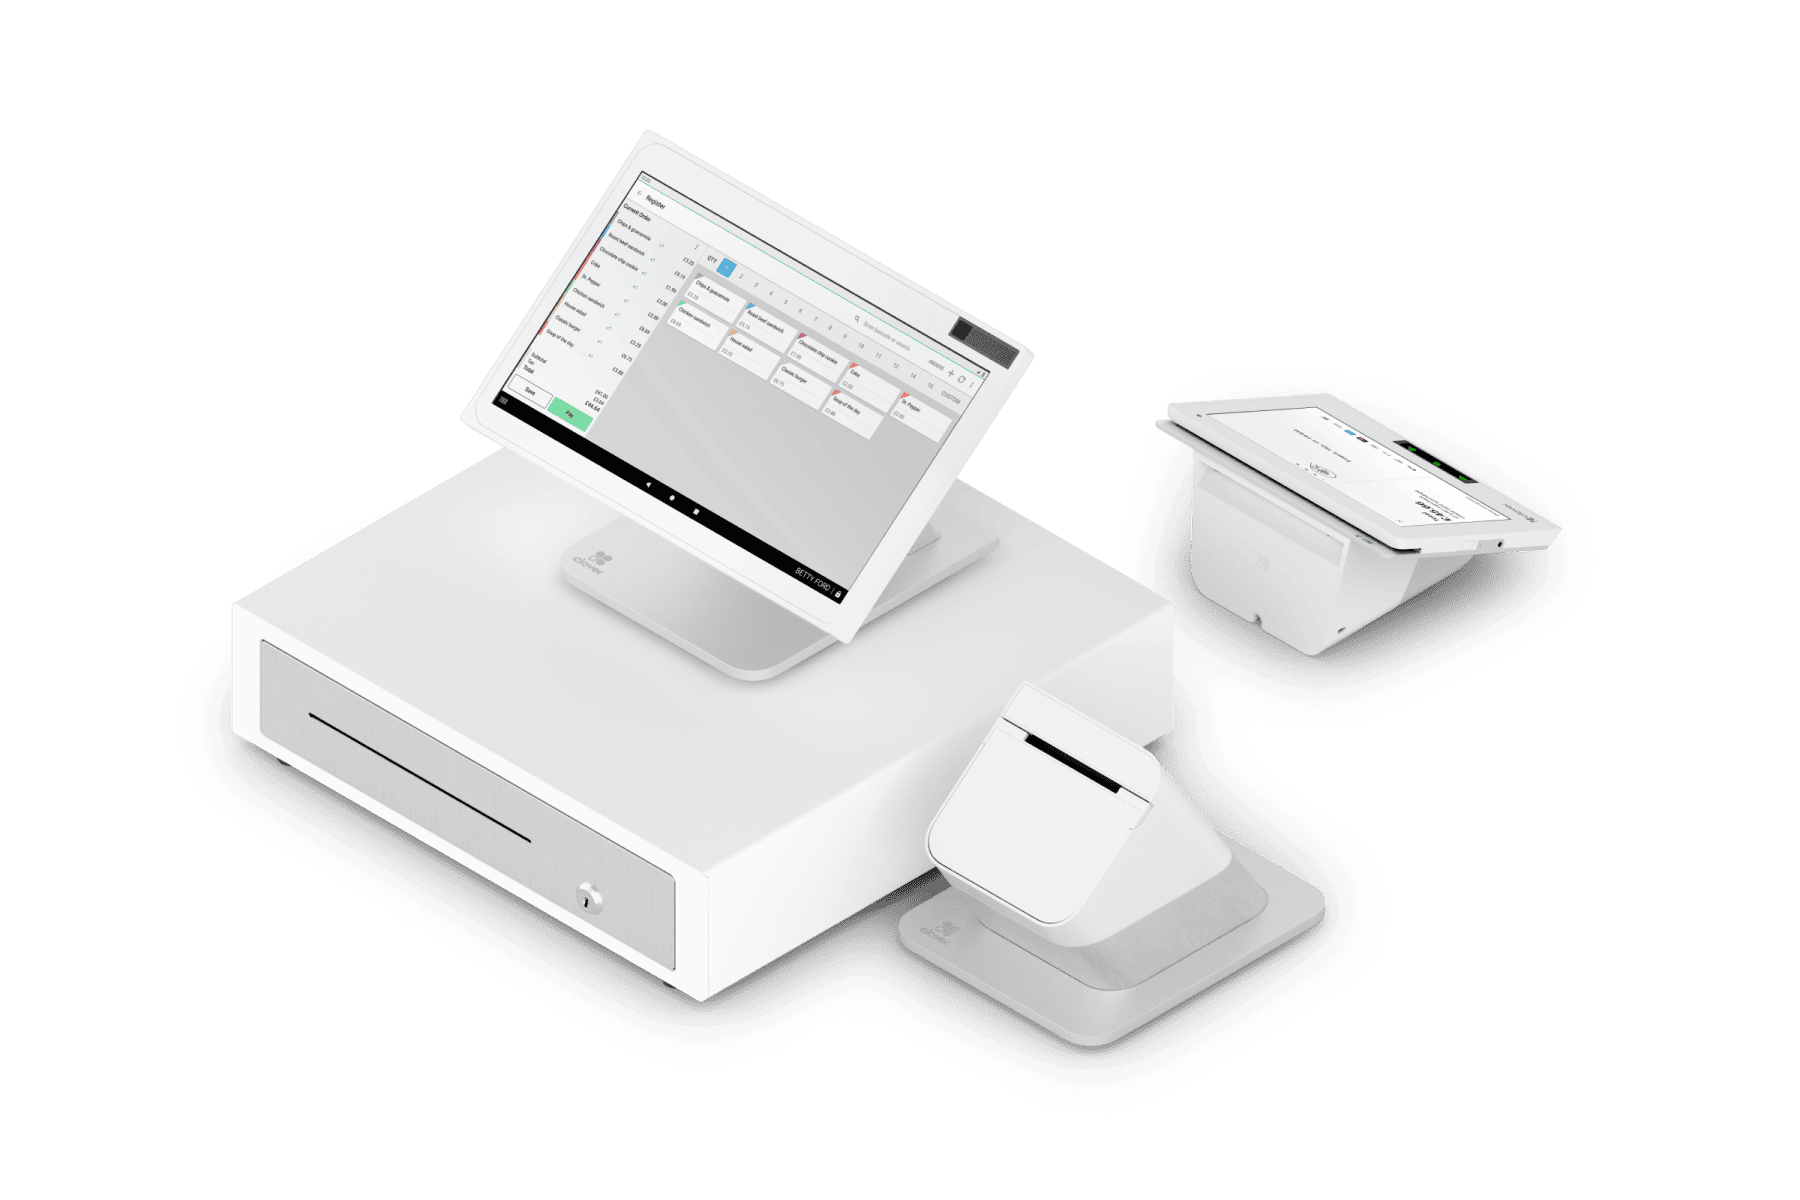
Dual-screen POS for busy checkout lanes
Fixed terminal for a till point, wired to the network and built to be left alone.
Handheld terminal for table service, delivery and anywhere payment happens away from the counter.
Pocket reader paired to a phone or tablet, for field service, markets and pop-ups.
Items marked as illustrative examples represent hardware categories Apex can source. Exact models, specifications and compatibility are confirmed during onboarding.
How it works
No obligation at any point, and no application submitted before you have seen what is going into it.
What you sell, how you sell it, and what your current payment arrangement looks like.
Your industry, ticket size, refund and dispute history and processing volume, against what underwriting will actually ask for.
The payment paths that fit your profile, with the trade-offs of each one set out plainly rather than one recommendation.
Account setup, gateway configuration and hardware, with the technical work done alongside you rather than handed over as a manual.
Monitoring, dispute handling and account reviews - and a route to a person when something needs one.
Apex does not guarantee approval, a rate, a saving or a timeline. Underwriting decisions are made by the acquiring institution, and Apex's work is to put the strongest accurate case in front of it.
Risk and disputes
Most merchant accounts are not lost over pricing. They are lost over a chargeback ratio nobody was watching until it was already too high.
Notice of a dispute while it can still be refunded or resolved, rather than after it has counted against your ratio.
Evidence assembled and submitted in the format the card networks actually accept, on their deadlines.
Screening rules, velocity limits and verification checks tuned to reduce fraud without rejecting genuine customers.
Routing and retry logic that responds to declines instead of simply passing them back to the customer.
Approval rates, declines and disputes visible across the account, rather than one statement a month.
Tracking against the thresholds that matter to your acquirer, with a warning before one is reached.
No provider can prevent chargebacks or guarantee a dispute outcome, and Apex does not claim to. These tools make disputes visible earlier and answer them properly.
Ecosystem
Apex works across processing, gateway and technology relationships so that a merchant is never dependent on one arrangement continuing to exist.
More than one acquiring path, so a single withdrawal does not stop a merchant taking payment.
Established gateways for routing, tokenisation and reporting, chosen for the business rather than for the commission.
Storefront platforms, billing systems and CRMs a merchant already runs, connected rather than replaced.
Terminals and readers sourced to match the processing arrangement they will actually run on.
Alerting and dispute tooling layered onto the account rather than bolted on after a problem.
Settlement paths for merchants accepting crypto alongside conventional payment methods.
Apex names a processing or technology relationship publicly only where doing so has been agreed with the organisation concerned.
How Apex works
Apex publishes customer quotes only once the merchant has agreed to them being used. Until then, here is what does not change.
Underwriting, integration and support are handled by the same team, and you can reach them directly.
Where the profile allows it, accounts are set up with a fallback, so one processor withdrawing does not stop revenue.
Apex does not promise approval, a rate or a timeline before underwriting has looked at your business.
Resources
How underwriting decisions are actually made, how to read what you are being charged, and how to keep a dispute ratio under control.
The parts of an application that decide the outcome, and the ones merchants spend time on that make no difference at all.
Interchange, assessments and markup, separated - so you can see which part of your rate is negotiable and which part never was.
Descriptors, refund policy, delivery evidence and alert handling: the four things that move the ratio, in the order they are worth fixing.
Questions
No. Most Apex merchants are conventional businesses - shops, restaurants, professional firms, e-commerce stores - underwritten and priced as exactly that. Apex also handles specialised and complex verticals, which is where the deeper capability shows, but a traditional business is not placed on specialised terms because of who else we work with.
Pricing follows underwriting. Card mix, average ticket, refund and chargeback history, the industry and how you take payment all feed into it. Apex does not quote a rate before seeing those, and does not guarantee a rate or a saving in advance.
No, and no payment provider can. Approval is an underwriting decision. What Apex does is prepare the file properly before it is submitted - the website, the policies, the documentation and the processing history - which is what usually decides the outcome.
That is a common reason merchants come to Apex. Where the profile allows it, accounts are set up with more than one processing path from the start, so a single withdrawal does not stop revenue while a replacement is arranged.
Yes, where the business qualifies for each. Card, ACH, eCheck and digital-asset settlement can run alongside one another under the same merchant relationship, with the gateway routing between them. What is available depends on the business type and underwriting.
Usually. Apex integrates with established storefront platforms, billing systems and CRMs, and does direct API work where an off-the-shelf plugin does not fit. Replacing a working system is rarely the right recommendation.
It depends on the industry and how complete the documentation is when it is submitted. A conventional business with its paperwork in order moves quickly; a specialised vertical takes longer because the file has to be prepared properly. Apex gives a realistic expectation up front rather than a headline number.
Alerting where the card network and issuer support it, structured evidence submission for disputes, and monitoring of the ratio across the account so a problem is visible before it threatens the merchant account. No provider can prevent chargebacks, and Apex does not claim to.
Get started
A short conversation is usually enough to tell whether Apex can improve on your current arrangement - and if it cannot, we will say so.
No obligation, and no application submitted without your agreement.
Tell us how your business takes payment today and we will review suitable options with you. No obligation.